31 January, 2025

Applicability of the Triangulation Simplification Provisions


As the name implies, the triangulation simplification provisions set out in Council Directive 2006/112/EC (the “VAT Directive”), provide for the application of an exempt intra-Community acquisition in the country where the transport of goods ends. It is effectively a simplification which avoids a VAT registration for party B which makes an acquisition of goods followed by a domestic supply in the country where the transport ends. Subsequently, the VAT liability on the domestic supply taking place in that country, shifts onto party C.

The triangulation simplification applies in the context of a chain transaction, specifically where three independent parties, A, B, and C, identified for VAT purposes in three different Member States transact with one another in a supply of goods between A and B, and B and C, with the goods being dispatched/transported from A’s Member State and ending in C’s Member State. As can be noted, a basic triangulation scenario entails two supplies with only one intra-community transport. In this article we will be surveying the pertinent VAT Directive provisions and how to apply them in practice as well as pointing out any pitfalls that may impact our conclusions.

As stated above, the triangulation simplification is applicable insofar as three separate taxable persons are identified for VAT in three different Member States, carry out two consecutive supplies with one cross-border transport. The transport, in the context of this tripartite transaction must be ascribed to one of the supplies and in order for the triangulation simplification to apply it must be ascribed to the first supply.  As a result, the cross-border transport is carried out either by A, B or any person acting on their behalf (such as a logistics company). If the IC transport were to be carried out by party C, the simplification cannot be applied.

It follows that, Article 141 of the VAT Directive sets out the conditions that must be met for the simplification to apply. Let us examine the following typical scenario in the context of these conditions:
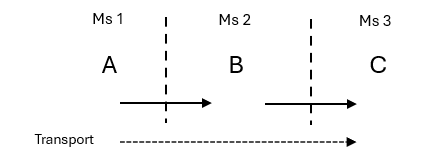
  • Acquisition of goods in MS 1 is made by B, a taxable person not established in MS 1 but identified for VAT in another MS, MS 2;
  • Acquisition of goods by B is made for the purpose of a subsequent supply in the MS where the transport ends, MS 3;
  • The goods acquired by B are dispatched/transported from a MS other than the one where B is identified to the MS of C, MS 3;
  • C, to whom the subsequent supply is made is another taxable person who is identified for VAT purposes in MS 3;
  • C is designated by B as the person liable for the payment of VAT in MS 3 on the supply carried out by B (who is not established in MS 3).

Under the triangulation simplification:

  • A will be carrying out an exempt intra-Community supply to B with the transport ending in MS 3, with A being required to submit a recapitulative declaration in MS 1;
  • B is considered to be making an acquisition in the Member State where the transport ends (MS 3), which insofar as the acquisition is made for the purposes of a subsequent supply taking place in that Member State would be treated as an exempt intra-Community acquisition in terms of article 141 of the VAT Directive.[1]
  •  For the purposes of the domestic transaction taking place in MS 3, C becomes the person liable to pay the VAT on the supply accounting for it by reverse charge and deducting the input VAT in accordance with and to the extent of his right of deduction.

As already mentioned, the triangulation simplification is rendered inapplicable if the cross-border transport from the Member State of origin is carried by or on behalf of a third party. It is also to be ensured that at the point in time of the acquisition of the goods in the Member State of origin, the intermediary party already knows that he will be making a subsequent supply to the third party in the third Member State.

In conclusion, whilst the triangulation simplification and its application in practice may appear straightforward nevertheless some complications may arise where seeking expert advice, would be highly recommended.


[1] It is worth noting that some Member States do not allow the Article 141 exemption on the intra-Community acquisition by the middle party if the latter, notwithstanding not being established there, holds a VAT registration number in that Member State.


Author: Brandon Gatt, Partner, Zampa Partners
All News

View All

02 October, 2026

BOV Fund Services marks 20 years of growth...

...

Learn More
18 September, 2026

BOV and Malta FA strengthen discussion around legal and AFC matters in...

...

Learn More
15 September, 2026

First edition of the BOV social week turns employee action into commun...

...

Learn More
14 September, 2026

BOV inaugurates second Home Finance Hub in Gżira...

...

Learn More

All News

View All

Sponsored Content

02 October, 2026

BOV Fund Services marks 20 years of growth...

...

Learn More

Sponsored Content

28 September, 2026

BOV Club returns to Freshers’ Week...

...

Learn More

Sponsored Content

18 September, 2026

BOV and Malta FA strengthen discussion around legal and AFC matters in...

...

Learn More

Sponsored Content

15 September, 2026

First edition of the BOV social week turns employee action into commun...

...

Learn More

upcoming events

View All

Upcoming Events

19 October, 2026

Digital Workshop 5: Transform Smarter - A Practical Roadmap for Digital Growth

...

Learn More

Upcoming Events

28 October, 2026

Do Not Look Away - Gender-Based Violence is also a Business Issue

...

Learn More

Upcoming Events

29 October, 2026

Digital Workshop 6: Securing the Future - Cybersecurity, Cloud & Responsible AI

...

Learn More

Upcoming Events

05 November, 2026

Smarter Regulation, More Agility

...

Learn More

upcoming events

View All

19 Oct
upcoming event 19 October, 2026, 08:30 AM

Digital Workshop 5: Transform Smarter - A Practical Roadmap for Digital Growth

Learn More
28 Oct
upcoming event 28 October, 2026, 08:30 AM

Do Not Look Away - Gender-Based Violence is also a Business Issue

Learn More
29 Oct
upcoming event 29 October, 2026, 08:30 AM

Digital Workshop 6: Securing the Future - Cybersecurity, Cloud & Responsible AI

Learn More
05 Nov
upcoming event 05 November, 2026, 08:30 AM

Smarter Regulation, More Agility

Learn More